CPA

Reverse mortgage strategy for business exit planning

When your clients have home equity and need liquidity for business transactions or exit planning, a reverse mortgage can be a tax-efficient solution. We coordinate transparently with you to ensure alignment with overall tax and financial strategies.

The Challenge

Your clients have significant home equity, but converting or leveraging that equity creates complexity. They might face unexpected tax consequences, need immediate liquidity for business transactions, or need to clear liens before closing a sale. How can you help them access that home equity efficiently without triggering unnecessary tax liability or disrupting their financial strategy?

Case Study: Business Sale & SBA Lien Clearance

The Situation

A restaurant owner, too young to qualify for a HECM, had taken out an SBA EIDL during COVID. The loan came with a blanket UCC-1 lien on all business assets. Now he had negotiated a purchase agreement to sell the restaurant. But the SBA lien created a 60-90 day payoff and lien release process that was holding up the transaction. The buyer was getting impatient, and the deal was at risk of falling apart. The owner needed a way to clear the SBA from the transaction immediately so the sale could close on schedule—and keep 100% of the sale proceeds for his retirement.

The Coordination

The restaurant owner's CPA called Renee to explore using a reverse mortgage to pay off the EIDL before closing. Renee explained the process clearly and coordinated directly with both the CPA and the owner. There were no surprises—everyone understood exactly what would happen, when it would happen, and how it would impact the overall transaction. The CPA stayed informed throughout, ensuring the reverse mortgage solution aligned with the tax strategy and exit plan.

The Solution

Solution: A proprietary (private) reverse mortgage on the owner's home. Because he was under the HECM's minimum age of 62, a proprietary loan was the right fit. The owner accessed home equity immediately to pay off the SBA EIDL before closing. This cleared the SBA lien from the transaction entirely. The buyer received clean title. The deal closed on schedule with no delays. Because reverse mortgage interest accrues rather than being paid monthly, there is no deduction along the way; any deduction would come only when the interest is actually paid, and only to the extent IRS rules allow based on how the funds were used. Those details were reviewed with the CPA.

The Results

The deal closed on schedule. EIDL paid off. Clean title transferred to buyer. The restaurant owner kept 100% of the sale proceeds as his retirement nest egg—no SBA lien eating into his liquidity or creating ongoing obligations. The tax and financial planning strategy stayed intact. Any future tax treatment of the reverse mortgage interest stays with the CPA to plan for at payoff. The CPA maintained the role as primary advisor throughout, with clear coordination from Renee every step of the way.

Deal Closed on Schedule

No delays from SBA lien release process

100% of Proceeds Retained

No SBA lien eating into sale proceeds

How This Works for CPAs

Home Equity Conversion Mortgage (HECM)

A HECM is a reverse mortgage insured by the FHA. It allows homeowners 62+ to access home equity without monthly mortgage payments. Funds can be accessed as a lump sum, line of credit, or monthly payments. For your clients, the key advantages are flexibility (they control when and how funds are accessed) and timing control (interest accrues instead of being paid monthly, and any deduction is generally available only when the interest is actually paid, typically at payoff, subject to IRS rules on how the funds were used). Unlike a traditional home equity loan or HELOC, there are no monthly payments required, and the loan only comes due when the home is sold or the owner moves out.

As a CPA, you understand that home equity is often your client's largest asset—but it's illiquid. A reverse mortgage can be a tax-efficient way to access that equity without triggering capital gains (since it's a loan, not a sale), without creating ongoing monthly payment obligations, and without disrupting retirement cash flow. This strategy coordinates well with overall tax planning, business exit strategies, and retirement income planning.

Client-ready explainer

Share with clients: why reverse mortgage proceeds are loan advances rather than income, and how that interacts with Social Security, Medicare and means-tested benefits. Proceeds, income and benefits →

Why CPAs Work With Renee

✓

She understands tax implications

Renee knows that HECM interest is generally deductible only when it's actually paid, typically at payoff, and only within IRS limits, and she coordinates with your tax planning around that. She doesn't push reverse mortgages that don't make tax sense for your client's situation.

✓

Direct coordination with you

She calls your office, not just your client. You stay informed and in control. No surprises or conflicting advice. You're the primary advisor; she's the coordinating specialist.

✓

She handles complex scenarios

Business sales, multi-generational assets, SBA liens, exit planning complications—she has expertise in scenarios that matter most to your clients. Not just simple reverse mortgages.

✓

She respects your role

You're the primary advisor. She's coordinating expertise. This clarity prevents conflicts and builds trust with your clients. Your relationship stays strong.

Questions CPAs ask

Are reverse mortgage proceeds taxable income?

No. Reverse mortgage advances are loan proceeds, not income, so they don't show up as income on the return (IRS Publication 554, Reverse Mortgages). Because it's a loan rather than a sale, drawing on the equity doesn't trigger capital gains either.

When is reverse mortgage interest deductible?

Generally only when it is actually paid, which for most borrowers is when the loan is paid off, and only within the IRS home mortgage interest limits (IRS Publication 936). Accrued interest that hasn't been paid isn't deductible year to year. That timing can matter for an estate or heirs who pay off the loan.

Can a reverse mortgage pay off other debts before a business sale?

Yes, once any existing mortgage on the home is paid off at closing, the remaining proceeds can be used for any purpose, including retiring business debt. For a HECM the youngest borrower must be 62 or older and the home must be their primary residence. Timing depends on HUD counseling, the appraisal and underwriting, so bring Renee in early when a sale has a deadline.

Does a reverse mortgage affect means-tested benefits?

The proceeds aren't income, but money drawn and left in a bank account past the month it's received can count as a resource for programs like SSI (SSA: SSI spotlight on loans). Funds left in an unused line of credit generally don't. A client-ready explainer is on WikiReverseMortgage.

General education, not tax, legal or investment advice. Rules can change; last reviewed October 2026.

Renee's Expertise

Certified Reverse Mortgage Professional with 20+ years of specialization in reverse mortgages, HECM, and proprietary loan products. Specializes in complex coordination with professional advisors.

CRMP® Founder, CRMS™ Designation Published Author 20+ Years Experience

Ready to Explore Reverse Mortgage Coordination?

Have a client situation where home equity and liquidity need align with tax planning? Let's discuss how we can coordinate to find the right solution.

Schedule a Consultation
Renee Konstantine, CRMP®

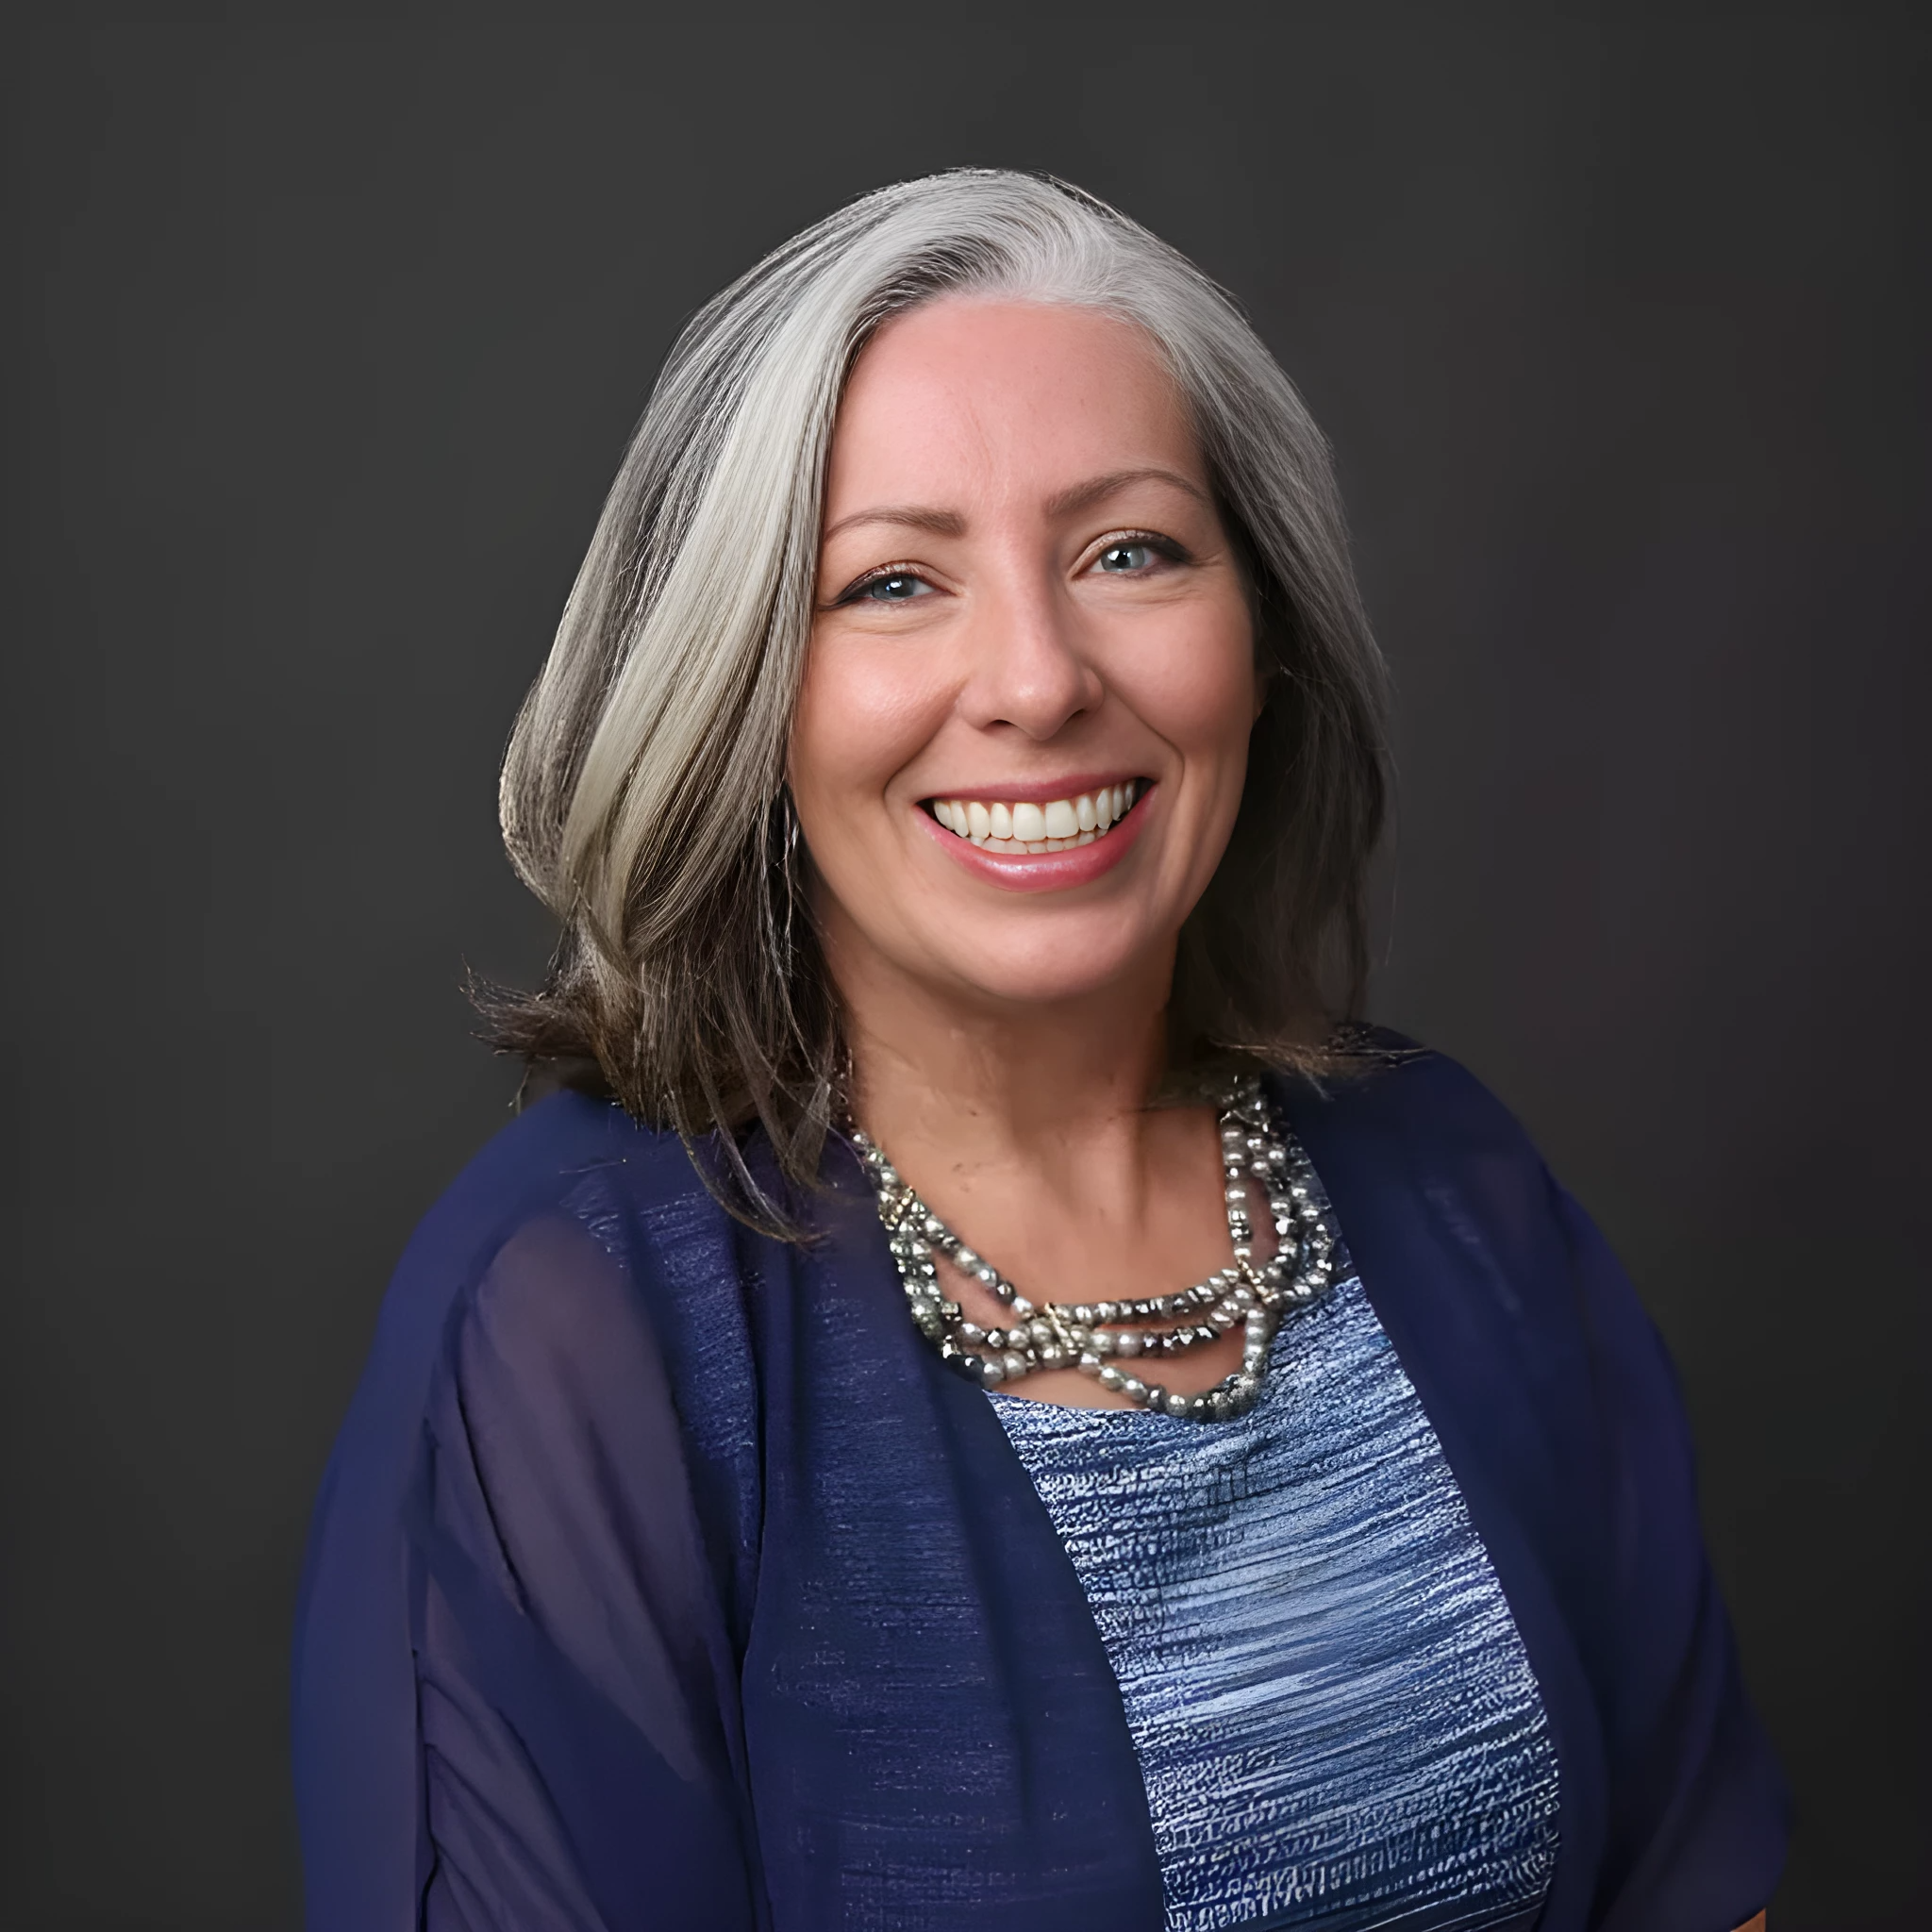
Renee Konstantine

CRMP® Reverse Mortgage Specialist

Certified Reverse Mortgage Professional with 20+ years specializing in HECM, proprietary reverse mortgages, and professional coordination with CPAs, CFPs, estate attorneys, and fiduciaries.

NMLS #1360025 | CA DRE #01343046
Licensed in CA & WA | Associate Broker, C2 Financial Corporation